Mortgage Financing. Simplified.

Let us guide you through the complex world of mortgage financing.
LET'S CONNECT

The mortgage process can be intimidating. We can help you get the right mortgage when you follow my 3 step plan.

Get started right away

The best place to start is to connect with Erica directly. As the mortgage process is personal, our commitment is to listen to all your needs, assess your financial situation, and provide you with a clear plan forward to secure financing.

Get a clear plan

Sorting through all the different mortgage lenders, rates, terms, and features can be overwhelming. Let us cut through the noise, we'll outline the best mortgage products available with your needs in mind.

Let me handle the details

When it comes time to arranging your mortgage, we have the experience to bring your financing together. Our goal is to make sure you know exactly where you stand at all times. No surprises. We've got you covered.
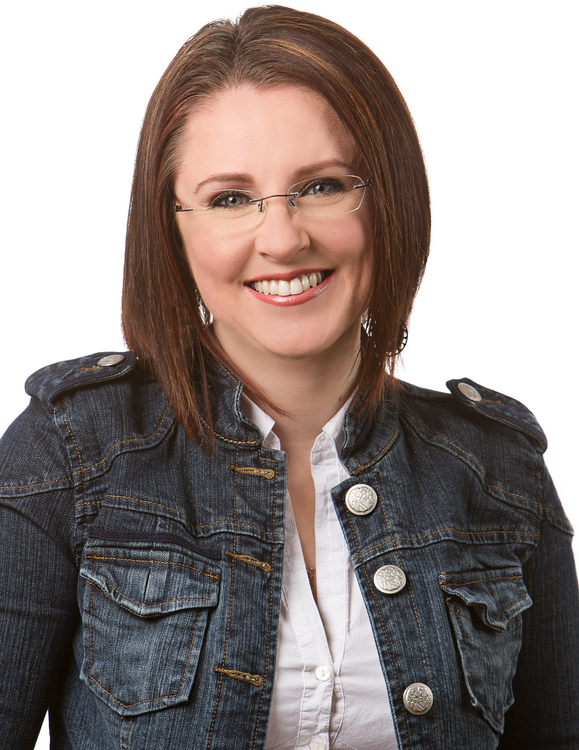
Mortgage Agent Level 2 Licence # M16000607

In 2016, I joined The Mortgage Advisors in Petawawa and I enjoy being a part of helping people achieve their dreams of homeownership. In 2018 I partnered with Erica Vincelli and together we are the perfect balance of skills.


Oftentimes, mortgage financing can seem confusing and overwhelming, especially as buying a home is one of the biggest financial decisions you’ll make. We embrace the challenges and would love the opportunity to guide you through all your mortgage options.


We specialize in working with First Time Home Buyers and military families. Not every mortgage is created equal, and the lowest rate isn’t always indicative of mortgage suitability. The goal is to find the mortgage product that best suits your long term needs and lowers your overall cost of borrowing.


Let us help find the best mortgage for you!
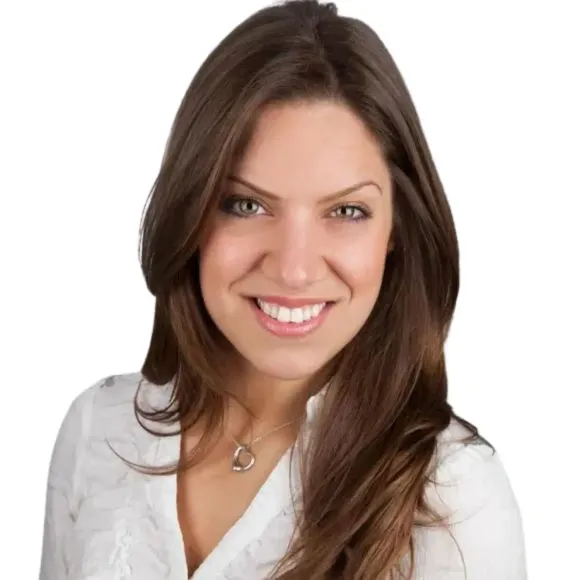
Erica Vincelli

I’m an award-winning, licensed mortgage agent, born and raised in this beautiful city of Ottawa. As a homeowner, real estate investor and landlord since the age of 21, I understand and have personally experienced many of the same struggles of obtaining a mortgage through the banks. 

When options are not properly explained, you may get trapped in a high penalty mortgage or worse, one you can’t get break free from at all. The fine print can be the most important detail and my team and I are here to provide clarity and do the hard work for you.


Having a passion for helping people, a love for numbers and real estate and the confidence to negotiate for your best mortgage, you will feel assured that you have the right people working for you. I am determined to change the way you experience and understand your mortgage and happy to share my 5-Star Reviews as they are proof of that commitment. My intention is to help you achieve your mortgage goals, whether it is to build a real estate portfolio or be mortgage free faster. I find ways to help you save money and time, and enjoy the process along the way.

When you put your trust in my team, you will be treated with respect while receiving ongoing communication and updates, all from the comforts of your home or work so that your life is not interrupted because the most important part of this process should not be getting the mortgage but rather the excitement of owning your very own home.


My name is Erica Vincelli and I am YOUR mortgage advisor.

LET'S CONNECT

Some nice things clients have said about Us.

Mortgage financing for the Canadian Armed Forces

We have considerable experience arranging mortgage financing for members of the Canadian military. I'd love to work with you!
LET'S CONNECT

Mortgage services to meet your needs.

Whether you're looking to purchase a property, refinance an existing mortgage, or if your mortgage is up for renewal, you've come to the right place. Select from the options below.

Run some calculations.

I'm just getting started.

Find out how much you could afford in 30 seconds.

I have a specific home in mind.

Find out if you can afford it in 30 seconds.

I want to refinance a home I own.

Find out how much you can take out in 30 seconds.

The best place to start the mortgage process is to contact me directly.

LET'S CONNECT
We'll be your guide through the entire mortgage process.

Articles to keep you learning.
By Lindsey Cupelli • November 11, 2026
Missed a Credit Card or Line of Credit Payment? Here’s What to Do If you’ve missed a payment on a credit card or line of credit and you’re worried about how it might affect your credit—or your future mortgage—this is for you. First things first: 👉 If you currently have an overdue balance, log in and make the minimum payment now. Seriously. Do that first. Everything else can wait. If You’re Only a Few Days Late Here’s the good news: Credit bureaus don’t record late payments until they reach 30 days past due. So if you missed a due date by a few days and paid it as soon as you noticed, it typically won’t show up on your credit report as a late payment—as long as you’re under the 30-day mark. That said, it never hurts to double-check. You can call your credit card company, explain what happened, and confirm the account is back in good standing. If you normally pay on time, they may even reverse the interest charged. It doesn’t hurt to ask. If You’re 30, 60, or 90 Days Behind If payments have gone past 30 days, your credit has likely been impacted—but the situation is still fixable. The most important step is to: Bring all accounts current as soon as possible Make at least the minimum payment on every account The faster you catch up, the more you limit the damage. Ignoring missed payments only makes things worse. If Cash Flow Is Tight If you’re struggling to make payments, communication matters. Contact your lender and keep them informed—even if you can’t pay right away. Lenders are far more willing to work with you when you’re transparent. What hurts your credit most is silence . If lenders don’t hear from you after repeated missed payments, they may write the balance off as bad debt and send it to collections. Collections can significantly impact your credit and stay on your report for years. How This Affects Mortgage Qualification Repeated missed payments can make qualifying for a mortgage more difficult—but timing matters. Once you’re back to making regular, on-time payments: Your credit can improve over time The impact of past mistakes becomes less significant If you’re planning to buy a home in the next couple of years, addressing credit issues early gives you far more options later. Final Thoughts Missing a payment doesn’t mean you’re “bad with money,” and it doesn’t mean homeownership is off the table. What matters most is how quickly you respond and how consistent you are going forward . If you’d like help reviewing your credit report or understanding where you stand from a mortgage perspective, feel free to connect. I’d be happy to walk through it with you and help you create a clear path forward.
By Lindsey Cupelli • November 4, 2026
Porting Your Mortgage: What You Need to Know Before You Rely on It Porting a mortgage means transferring your existing interest rate, remaining term, and outstanding balance from your current home to a new one when you sell and buy again. While some lenders—especially big banks—make porting sound simple, the reality is that porting a mortgage is often complex and far from guaranteed . It’s not a magic solution, and it doesn’t mean you automatically get to keep your old mortgage on your new home. In many ways, porting a mortgage feels like applying for a brand-new one—often with more conditions . Here’s why. 1. You Still Have to Re-Qualify Even though you already have the mortgage, the lender will reassess you. If you: Changed jobs Moved to a new city Are on probation Switched industries or income types …the lender may decline the port. Your previous approval does not carry over automatically. 2. The New Property Must Be Approved The lender also reassesses the new property . Just because they accepted your previous home as collateral doesn’t mean they’ll approve the next one. Expect: A new appraisal A review of the property’s condition Scrutiny around marketability and value If the lender isn’t comfortable with the property, the port can fail. 3. Property Values Rarely Line Up Perfectly Most moves involve a price difference. Buying a more expensive home: You’ll likely need additional funds at a blended rate, which can increase your payment. Buying a less expensive home: You may face a penalty for reducing the mortgage balance. Either scenario can affect your costs. 4. You Still Need a Down Payment Porting doesn’t mean you “swap houses” without cash. You still need: A down payment on the new purchase Closing costs Funds available at the right time This often surprises buyers. 5. Penalties Usually Still Apply (At First) Most lenders: Charge the full mortgage penalty when you sell Refund it only after the port is successfully completed If you’re relying on sale proceeds for your down payment, this temporary penalty can create a cash-flow issue. 6. Timelines Rarely Line Up Perfectly Real estate markets don’t cooperate. You might: Sell quickly but struggle to buy Find a home quickly but wait months to sell Closing dates rarely align, which complicates porting even further. 7. Port Periods Vary by Lender This is where the fine print matters. Depending on the lender, the port window may be: Same day only 30 days 90 days Up to 6 months If the port window is short, both transactions must close within that timeframe—or the port fails. Longer port periods offer flexibility, but also carry the risk of selling first and not finding a replacement property in time. The Bottom Line Porting your mortgage can make sense—especially if you have a strong rate and are buying a similar-priced home. But it is not guaranteed , and it comes with conditions, risks, and timing challenges. Portability is a feature, not a promise. Before you rely on it, it’s important to review all your options , including whether staying with your lender actually makes financial sense. If you’re planning to sell and buy, I’d be happy to walk you through the process, explain your options clearly, and help you decide whether porting is the right move—or if another strategy makes more sense.
By Lindsey Cupelli • October 28, 2026
On October 28, 2026, the Bank of Canada raised its key interest rate by 0.25%, bringing it to 2.5%. If you have a mortgage, are shopping for a home, or have a renewal coming up, this decision matters. Here is a plain-language look at what changed, why it happened, and what it could mean for you.
Show More